For years, crypto regulation has revolved around whether a digital asset is a security.
Regulators, lawyers, and crypto companies have debated this, often reaching different conclusions based on how they interpret existing laws.
I have watched this argument evolve, and RWA tokenization may be the development that complicates it most.
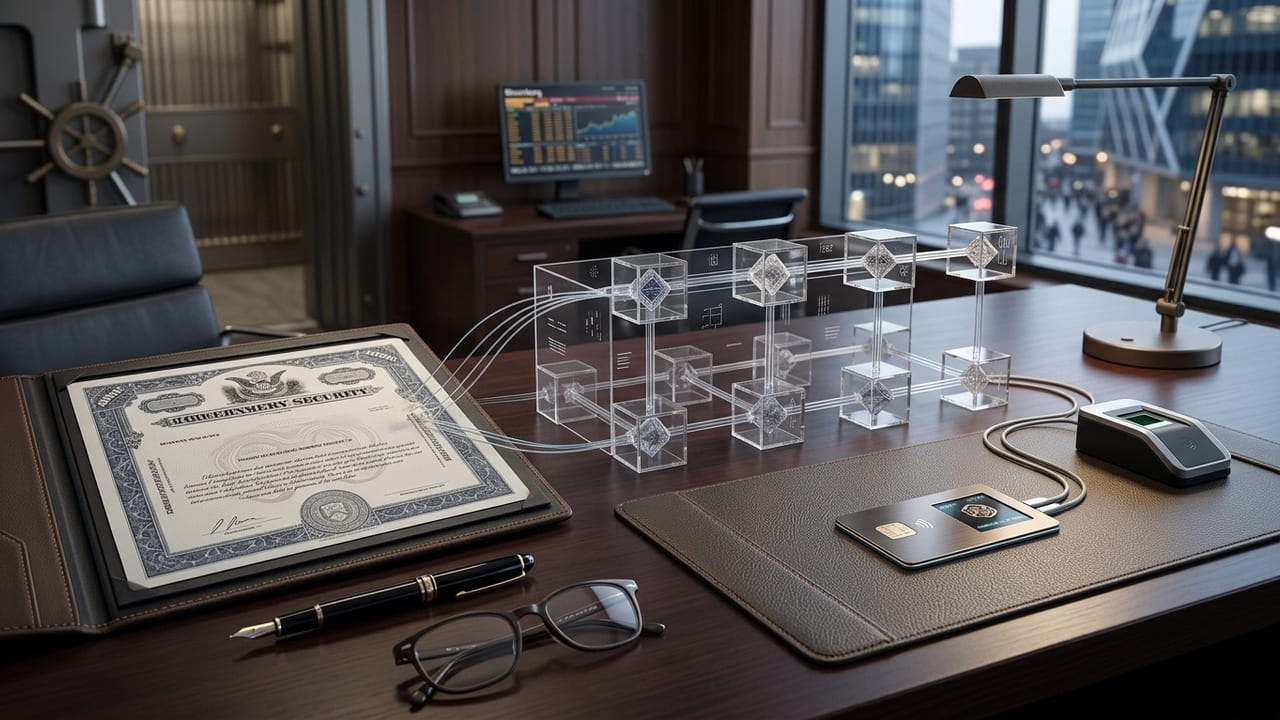
When you tokenize a stock, bond, fund, or credit instrument, the blockchain becomes less important than the asset itself. A tokenized bond is still a bond, and a tokenized fund is still tied to a financial product.
Putting an asset on-chain does not remove the laws that govern it, and this is where tokenization exposes the growing boundary between crypto regulation and securities law.
The question is no longer just whether something is “crypto.” It is which financial rules apply once traditional assets move on-chain.
This is becoming more critical as tokenization moves beyond experimentation. RWA.xyz shows tokenized RWAs have grown into a multi-billion-dollar market, led by categories such as U.S. Treasuries, private credit, and commodities.
Blockchain Changes the Infrastructure, Not Necessarily the Asset
A common misunderstanding about tokenization is thinking that putting an asset on a blockchain changes its legal nature. It does not.
A digital version of a Treasury fund is still tied to the actual Treasury fund, which means recording ownership on a blockchain does not remove investor protections, disclosure rules, or existing financial responsibilities.
The U.S. Securities and Exchange Commission has recognized this challenge in talks about tokenized securities. They understand that blockchain technology can represent ownership in traditional financial instruments.
This difference matters because tokenization is not building a brand-new financial system. Instead, it adds a new settlement and ownership layer to the system we already have.
BlackRock’s BUIDL fund is a good example. It uses blockchain to show ownership in a product backed by U.S. Treasury assets. Franklin Templeton has also tried blockchain-based fund infrastructure with its OnChain U.S. Government Money Fund.
These examples show institutional tokenization is moving closer to regulated finance.
The Hard Part Is Not Moving Assets On-Chain
The technical side of tokenization, like creating a token, setting up a smart contract, and recording ownership on a blockchain, is no longer the hardest part.
The difficult questions are legal:
- Who actually owns the asset?
- Who can transfer it?
- What happens if someone loses access to their wallet?
- Does the token holder have the same rights as a traditional investor?
- How are disputes handled across jurisdictions?
These are clearly financial and legal issues, and that is why tokenization could become one of the biggest challenges for crypto regulation.
The industry is shifting from just creating new digital assets to rebuilding traditional financial products using blockchain. This means regulators need to look past the old crypto-versus-traditional-finance debate.
Meanwhile, many people in crypto believe that blockchain will replace traditional finance. But tokenization shows it’s more complex.
The future might not be about crypto beating TradFi. Instead, blockchain could become part of the infrastructure that supports traditional finance.
Major financial institutions are already moving in this direction. The Depository Trust & Clearing Corporation (DTCC), central to U.S. securities settlement, has been exploring tokenization services to support digital versions of traditional securities.
This brings a new regulatory challenge. If blockchain becomes part of mainstream finance, regulators cannot treat everything on-chain as a separate crypto category. Regulators need to understand how the token relates to the underlying asset.
Regulation Will Determine If Tokenization Grows
Tokenization’s success will depend not only on faster blockchains or better technology, but also on whether markets can create clear rules for ownership, compliance, and investor protection. The winners will be those that successfully connect blockchain efficiency with existing financial systems.
Tokenization reveals that the future of finance may not be fully decentralized or fully traditional. It actually could be a mix of both.
But for that future to happen, the industry needs to accept one important fact: putting an asset on a blockchain does not change what the asset is.
It only changes how the asset moves, settles, and interacts with the financial system. That is why tokenization is bringing crypto and securities law together.